What Does a £50,000 Employee Actually Cost?
21 October 2026
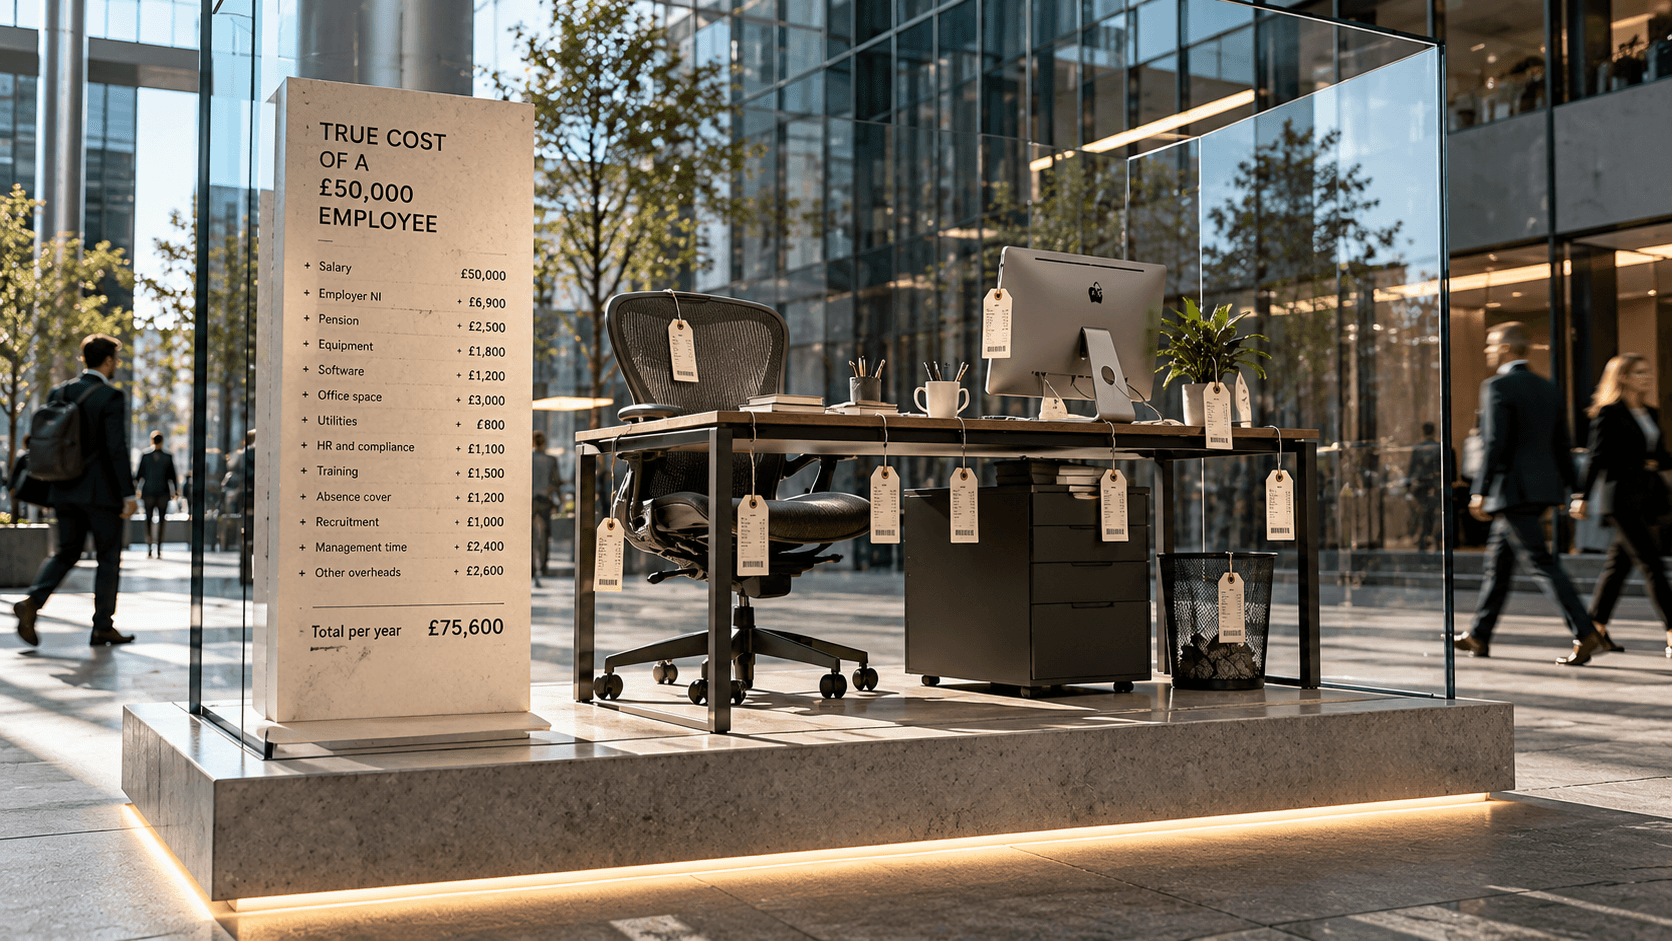
A £50,000 salary sounds straightforward.
You pay someone £50,000 a year. They do a job. Hopefully, they do it well. Everyone carries on.
Except that is not what the business has bought.
It has bought a person’s time, capability and attention. It has also taken on employer National Insurance, pension contributions, equipment, systems, support, recruitment effort and the management time required to get that person properly up and running.
The salary is the headline number. It is not the full price.
For the 2026/27 tax year, a standard employee on a £50,000 salary creates an immediate direct employment cost of roughly £58,000 a year before most of the things people mean when they say “employment costs”.
The salary is £50,000. Employer National Insurance adds around £6,750. Minimum employer pension contributions add roughly £1,313.
That takes the direct annual payroll cost to approximately £58,063.
And that is before the laptop, phone, software licences, recruitment costs, benefits, training, office space or the collection of “quick” onboarding meetings that somehow occupy three people for a fortnight.
The National Insurance figure assumes the standard 15% employer rate on earnings above the £5,000 secondary threshold. The pension figure assumes the statutory minimum employer contribution of 3% on qualifying earnings. The exact number will differ if an employee falls into a different National Insurance category, receives a more generous pension contribution or works for an employer able to use Employment Allowance.
This is not an argument that employees are expensive.
It is an argument that hiring is a bigger decision than the salary figure on the job advert suggests.
Small businesses understand this particularly well because they have less room to hide a poor decision.
A large employer may be able to absorb a bad hire somewhere in a team of 2,000. A business with 20 or 30 people feels it immediately. Hiring somebody senior can be one of the largest financial commitments the company makes that year. If the person is wrong, the role is unclear or the business has not thought properly about what it needs, the consequences are not confined to payroll. A project slows down. Customers wait. Other employees pick up work they should not be doing. The founder spends their week managing a problem rather than winning business or improving the company. Eventually, the business pays to recruit again.
That is why the real cost of a bad hire is rarely just six months’ salary. It is the opportunity cost.
The company loses time. It may lose momentum. It may delay a product launch, miss a sales opportunity or frustrate a customer. The exact financial damage varies, which is why anyone claiming that every bad hire costs a neat and universal figure is usually selling something.
But the basic point is hard to dispute: a cheap hire can become a very expensive one.
The opposite is also true.
A £60,000 employee can be outstanding value if they bring in a major customer, improve a failing operation, reduce costly errors, build a better team or free a founder from work they should have stopped doing years ago.
This is where salary conversations can become slightly ridiculous.
Businesses can spend weeks debating whether a candidate deserves another £5,000, then make an offer without agreeing what success should look like after six or 12 months.
That is backwards.
The better question is not, “Can we afford a £50,000 employee?”
It is, “What needs to become true for this person to be worth £58,000, £65,000 or more in the first year?”
Not every employee needs to generate revenue directly.
A finance manager will likely never make a sale. An operations lead may not bring in a client. A brilliant executive assistant might not have a target in the CRM.
But every role should have an economic purpose.
A finance manager might improve cash flow, reduce risk and stop the founder making expensive decisions on instinct. An operations lead might remove bottlenecks that let the business serve more customers without adding chaos. An assistant might give a senior person back ten hours a week, allowing them to focus on sales, strategy or delivery.
The return can be revenue. It can be margin. It can be time. It can be reduced risk. It can be better decisions.
What it cannot be is vague.
Before making an offer, a business should be able to answer a few basic questions.
What problem are we hiring this person to solve?
What will they own that nobody owns properly now?
What will be measurably better after 3-6 months?
What authority, support and information will they need to succeed?
And what happens if we do not hire them?
Sometimes the honest answer is that nothing serious happens. The work can be reorganised, automated, delayed or stopped. In that case, the business may not need a £50,000 employee.
Sometimes the answer is that sales stall, customers leave, delivery fails or the founder remains trapped doing work they should have delegated two years ago.
That is not a cost problem.
That is an investment case.
One final point: paid holiday is a legal entitlement, not a separate payroll surcharge on top of a salaried employee’s £50,000. Most workers are entitled to 5.6 weeks of paid annual leave. The cost is felt through lost working capacity or the need to pay for cover, overtime or a contractor, rather than as an extra payment added to the salary.
A £50,000 salary is only the price printed on the label.
The real question is what the business expects to get for buying it.